h1

Jerry Lynch – President, Magazine And Books, Retail Association – Explains Why “Magazines Are Still A Viable Product In The Marketplace” At The ACT 7 Experience…Linda Ruth Reporting…

May 3, 2017

With unit sales of 12.1%; the retail space allocated to the category down; the quality of space under fire, and a continuing buzz of negativity associated with print, it is no surprise that the sale of magazines at retail continues to be challenging. Jerry Lynch, the president of Magazine and Books, Retail Association (MBR), spoke with the audience at ACT 7 last week to analyze what is happening to magazines at retail, what the implications are, and how publishers might most effectively respond.

Retail is, in fact, under fire, not only for magazines but for all categories. E commerce is challenging brick and mortar sales. Trips to the store are mostly down, and, when at the store, the shopper basket size is down. While some growth is expected, most will come from stores less than 20,000 square feet—which could be a problem for categories fighting for attention in stores.

Efforts by stores to add departments have not been universally successful. Target, for example, invested in food, but people still don’t go to Target for food. “Just putting a product category in doesn’t change who you are,” Lynch said. Stores are getting people to go through the added departments, but not getting them to buy when in those departments.

How does digital contribute to the mix? Smart retailers are looking to digital commerce as their top place to add revenue. Another approach is to look to the categories where the internet can’t compete—for example, fresh foods and perishables. Retailers are reinventing the front end to move customers through and out quicker. And one promising venture is click and collect: the shopper can order online, and pick the order up at retail. The brick and mortar store locations provide instant gratification and a cost advantage through savings on shipping.

Still, publishers continue to be frustrated by retail, and find themselves asking: should I continue to invest? What is the opportunity?

Print magazines, Lynch told us, are still a category selling over $2 billion annually. We continue to sell over a million copies a day in 121,000 outlets. And there is hope to be found in other measurements as well. Magazine product is still profitable to retailers, the supply chain has dropped out costs, and retailers are looking for help. Magazines still make the retailer 62 cents per sale, compared to other categories, many of which are considerably lower.

And, Lynch said, we have great product. We might not talk about that enough, but we have value to offer our customers. Magazines offer many brands across the category, and our readers believe in the brands and are swayed by advertising. These are the customers retailers want.

What publishers can do is, instead of retreating, to seize the offensive. We can seize the opportunity, embrace retail, raise our expectations. We still have the opportunity to grow. To do so, we must establish our expectations and identify opportunities through benchmarking; we must collaborate with our partners across the supply chain, leading with the consumer in mind. We must communicate what we sell, attacking the impediments to opportunity. And we must celebrate what we have.

h1

Everything’s Gonna Be All Right (Just Different)

May 3, 2017

newsstandpromos's avatarFrom the Foredeck of the Titanic

Permanent Musical Accompaniment to this Post: 

I had the distinct pleasure of attending the Magazine Innovation Center’s ACT 7 conference at the University of Mississippi in Oxford, MS last week. The Magazine Innovation Center was founded in 2009 by Dr. Samir Husni of the University of Mississippi’s Meek School of Journalism in response to the crisis the magazine publishing industry found itself in after the start of the Great Recession of 2008. To me, the ACT conferences (ACT means Amplify, Clarify, Testify) serve two purposes: The first is to give a small group of magazine professionals a chance to meet together and exchange information about the business in a setting that is outside the usual “industry conference” setting. The second and in some ways more important one is to allow undergraduate and graduate students of journalism and magazine publishing a chance to learn from and interact with industry professionals.

This…

View original post 904 more words

h1

Making Magazines Make Money Again… ACT 7 Experience, Day 2, Part 2…

May 2, 2017

The Magazine Innovation Center’s ACT 7 Experience continued on Wed. April 26 with a panel discussion on Make Magazines Make Money Again… relive the panel…

h1

The Science of Touch, Adding Value To Your Magazine Brand, And Life Lessons Learned: ACT 7 Experience: Day 2 Part 1…

May 2, 2017

We continue in posting the Magazine Innovation Center’s ACT 7 Experience. Here is the three opening presentations from Wed. April 26, 2017… Stay tuned for more presentations…

Stay tuned for more presentations…

h1

CEO Of MEDIARadar, Todd Krizelman, Advises ACT 7 Attendees To “Go Towards The Light”…Linda Ruth Reporting…

May 2, 2017

“Go towards the light,” Todd Krizelman advised, echoing an earlier speaker at Mr. Magazine’s™ ACT 7 held at the University of Mississippi this week. Krizelman, the CEO of MEDIARadar, was present to review where print advertising stands in the US. “Opportunity is still there,” Krizelman said, “publishers need to study the benchmarks and look to where they might take advantage of it.”

Sure, print is down, print ads are down, but not across the board. For magazines, there are five distinct verticals—national consumer, B2B, regional, science, and enthusiast—and each have their own benchmarks, their own challenges, and their own opportunities. “For me, it’s misinformed when the press reports print is down,” Krizelman told the group of publishers and students gathered at the Meek School of Journalism. “All media is not the same. Each vertical is going through its own experience right now. Each B2B category has its own ecosystem of advertisers, and the five main verticals have different benchmarks.” The regional and enthusiast verticals are still showing strength, Krizelman continued; and although there’s been a four-year decline in ad pages across the board of 15%, almost half a million were purchased in consumer titles alone in 2017.

With more money available for advertising than ever before, these are the good days; but with media companies from the tech center competing for those dollars, snagging those bucks becomes a highly competitive endeavor. “My six year old doesn’t even understand the difference between TV and iPad,” Krizelman said. “Today YouTube is bigger than all of NBC plus 22 cable channels together, yet media companies till recently have not seen them as a competitor.”

But it’s important to understand that declines are not evenly distributed. Although the ad sales market is down in a lot of places, there are still areas in which it is level or up. Nationally, pharmaceutical, for example, isn’t down so much, while there’s been a big loss in apparel and accessories. And the publishers that are still making the most money are steering their businesses towards the light. In the food category, for instance, there is a lot of editorial competition, but last year there were almost 600 new advertisers and 256 existing advertisers increased their spend, giving new titles such as Hoffman’s Bake from Scratch the opportunity to thrive.

B2B: has remained much more stable over the last few years, with ad pages down a comparatively small (and unequally distributed) 6%. And in the regional vertical, a quarter million ad pages were placed last year. Regional titles are thriving in the regions where the economies are strong, and the largest advertisers for this vertical are retailers. IRetail is going down everywhere, which creates the challenge: retail advertising pages declined 25% in just one year. But ads for restaurants and bars are going up, real estate is up, and, region to region, we’re seeing the same story everywhere.

Krizelman’s advice to publishers is to study the number of new advertisers in the market each year, find out who and where they are, and go for them. There is more new business to be had than people realize. In Texas alone, 7000 new advertisers came on the scene. Learn the benchmarks, target those new opportunities, and strive to be as good as the benchmark.

“Know the key vitality metrics for your segment,” Krizelman advised. “What threatens your business? What are the opportunities to increase sales? Not all management is created equally—be the best in print. Study what others are doing that works. Innovate but also learn from others. Watch what they are doing and build on it.

“I view print with a lot of eager hope,” Krizelman finished. “I reject the idea that print is not fresh and innovative. If the product is created well, it creates user engagement, which makes advertisers want to be part of the magazine.”

h1

ACT 7 Experience: Day One. Magazines Matter, Print Matters.

May 1, 2017

The Magazine Innovation Center’s ACT 7 Experience is now history. What follows are the three first presentations of ACT 7 Experience. The welcoming remarks of the Magazine Innovation Center’s founder and director Samir “Mr. Magazine™” Husni, the welcoming remarks of Will Norton, Jr., the dean of the Meek School of Journalism and New Media, the opening remarks of Susan Russ, senior vice president, communications, MPA: The Association of Magazine Media, and the opening keynote address by Phyllis Hoffman DePiano, CEO, Brian Hart Hoffman, chief creative officer, and Eric Hoffman, chief operating officer of Hoffman Media.

Relive day one of the ACT 7 Experience. Enjoy.

h1

Jim Elliott Leads A Panel Of Experts On How To Explore Ways Publishers Can Make Money Again From Magazines…Linda Ruth Reporting From ACT 7 Experience…

May 1, 2017

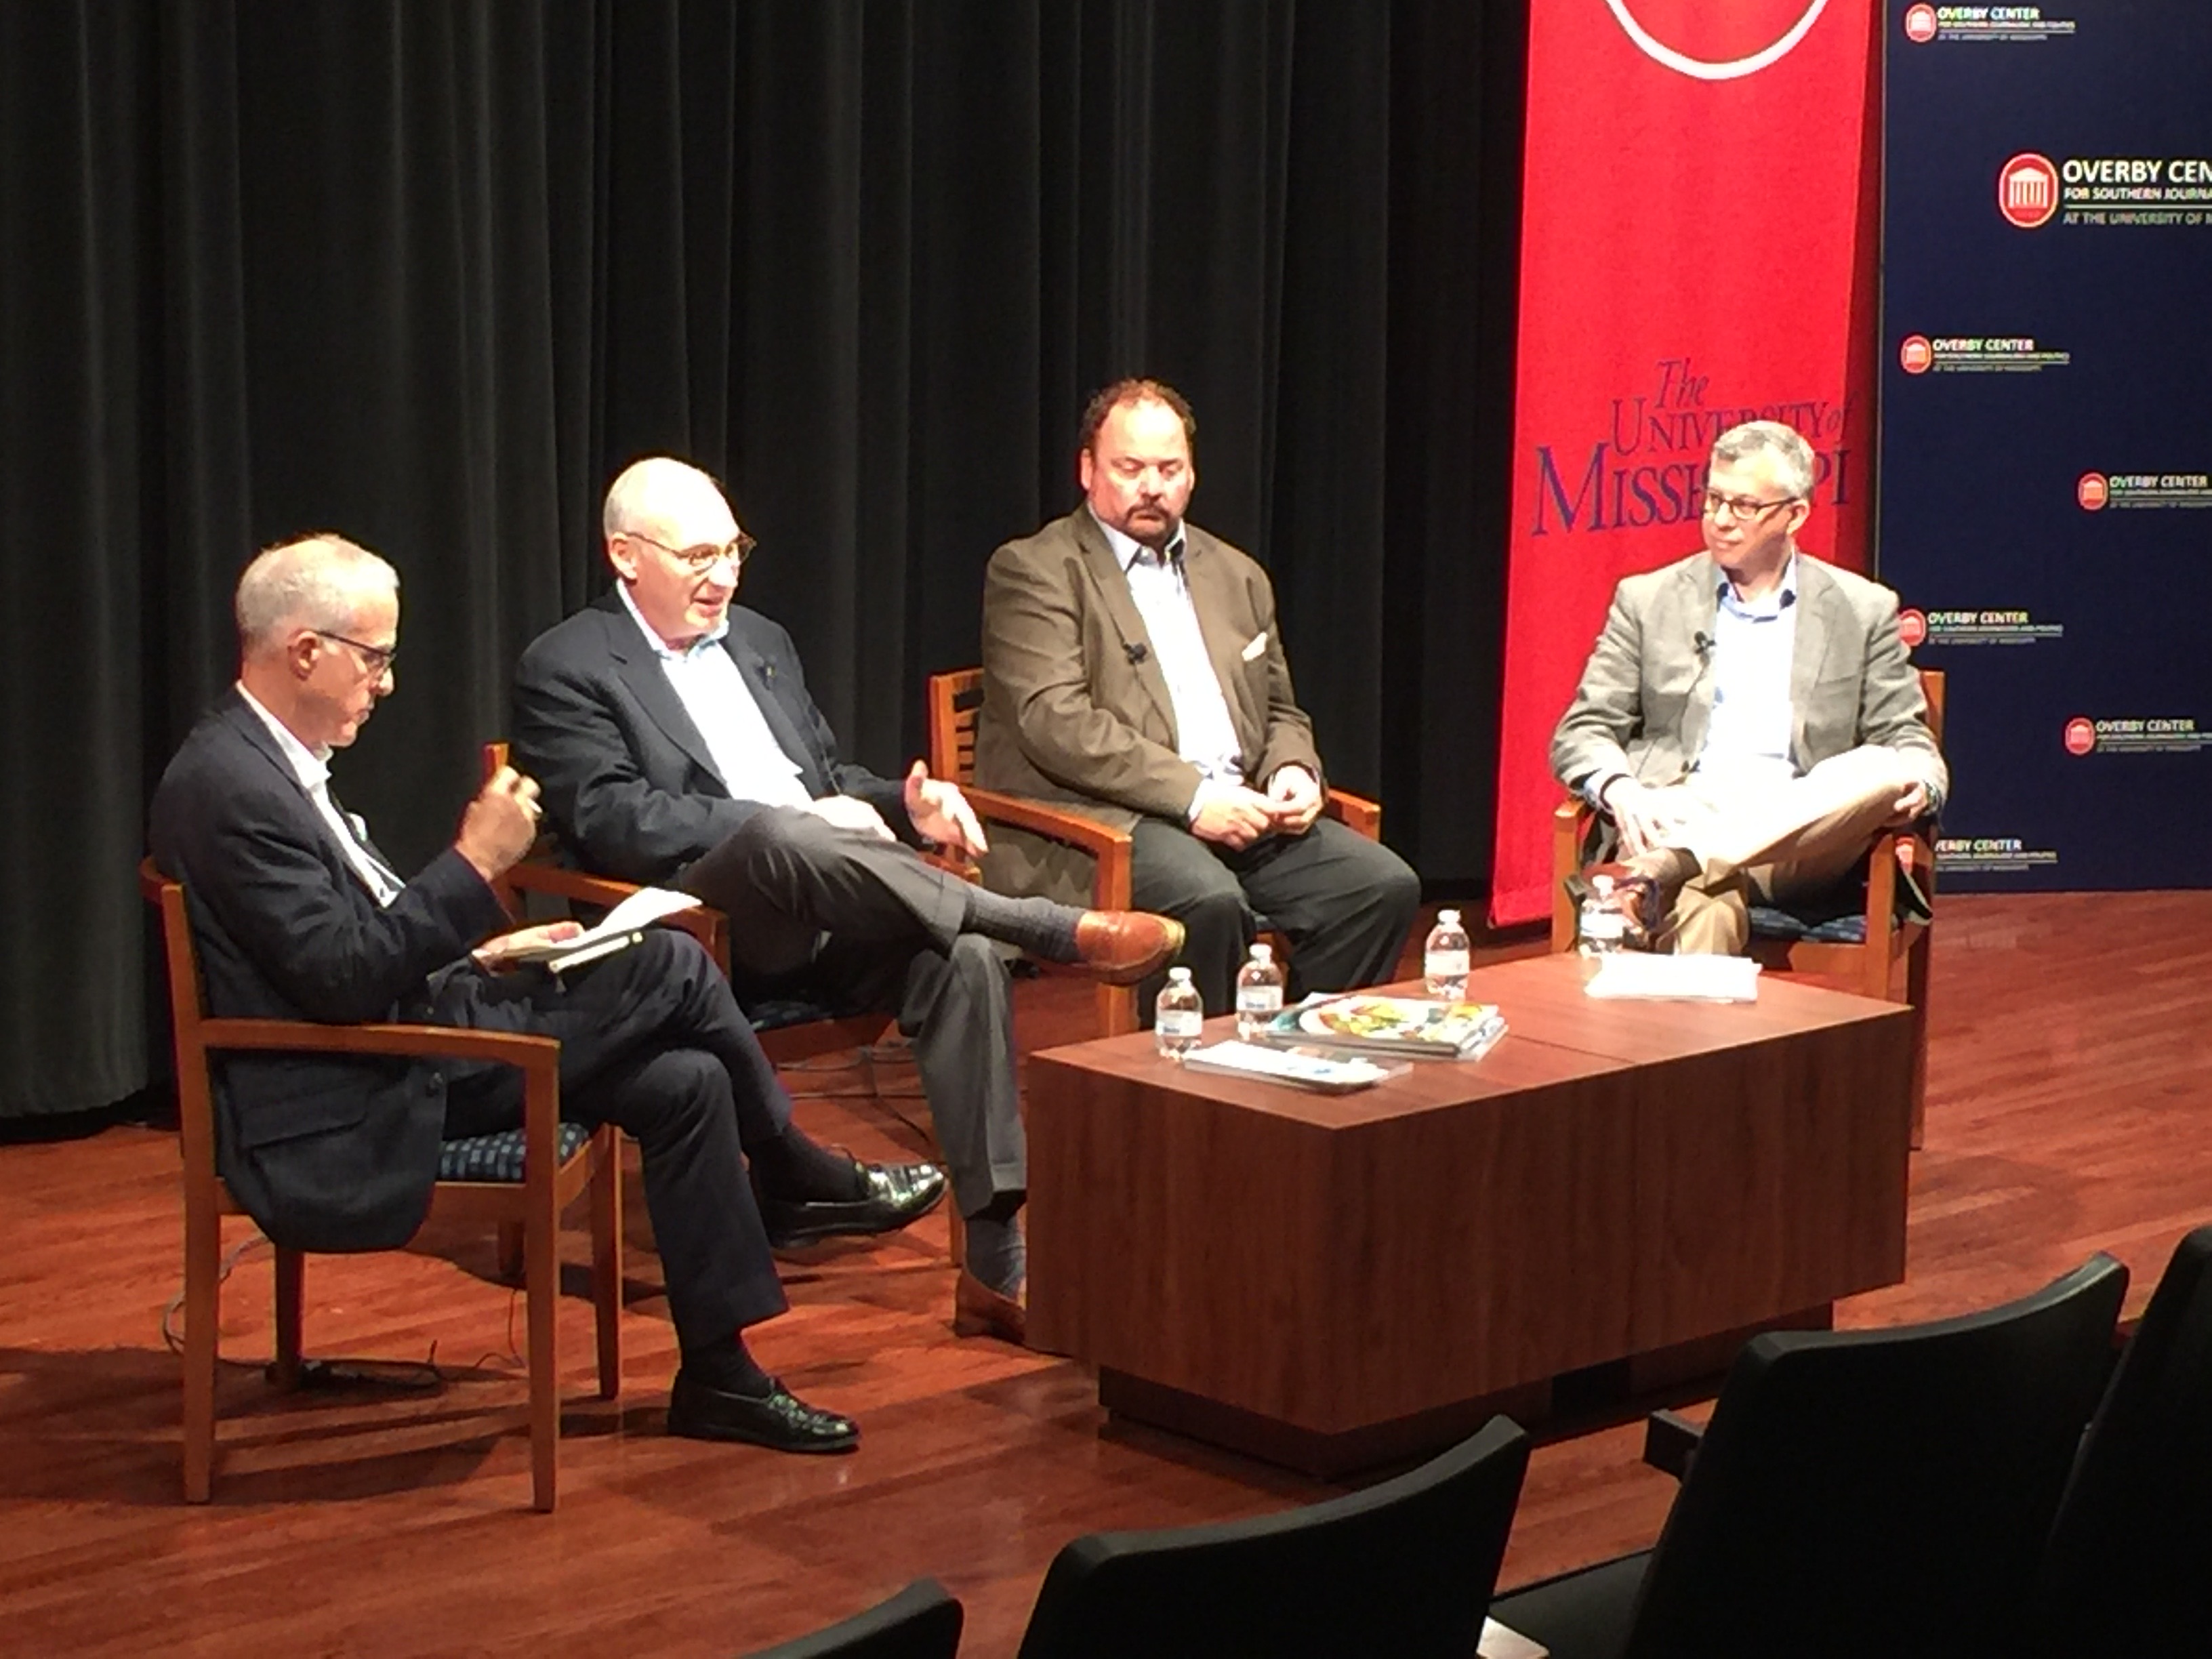
(Right to left) Dan Fuchs, John French, Steve Mayer, and Jim Elliott.

Jim Elliott, President of James G Elliott Co,.led a panel of industry experts to explore the ways in which publishers can make money again, at the Magazine Innovation Center’s ACT 7 Conference in Mississippi today. Panelists were John French, described as “a rock star in B2B”; Dan Fuchs, VP, publisher and chief revenue officer of HGTV magazine; and Steve Mayer, publisher of Plate magazine. What follows is from that panel discussion:

Elliott: We’ve been told to always run your business as if you’re going to sell it, even if you’re not. We have here representatives of both B2B and consumer publications. Operationally, what would you see as the difference?

Fuchs: A B2C company with a focus on the consumer offers a broader advertising base. We can deliver the consumer, who is interested in that which we aren’t necessarily writing about, whose interests include products outside the vertical product niche. It gives us the opportunity to cast a wider net.

French: B2B’s subject matter being smaller, more focused, and more targeted, delivers an ad base that is more narrow. But the worlds of B2B and B2C are starting to come together through data segmentation. I run into big B2C publishers who don’t know who their subscriber is. That’s changing; it needs to change, and it offers a valuable and targeted approach to advertisers whether in a B2B or B2C environment.

Elliott: What do you see emerging in terms of uses of new technology?

Mayer: Plate mag is in a B2B world, deeply invested in the restaurant industry. Its audience is tactile, tied into the sights, sounds, and smells of the restaurant kitchen. The print magazine, with its tactile nature, has a natural connection, and replicating the experience on line has been a challenge. To meet it, we essentially had to re-invent the site.

Fuchs: There’s still a great deal of profitability in print ad revenue. We’re able, in the publication, to use different varnishes for paint advertisers, for example, giving a tactile experience to introduce a tactile product. We use it to surprise and delight; we look to the consumer for what he or she really wants, and we deliver that.

French: The number one way to get and keep a database of good names is to send a good quality magazine. Whether B2B or B2C, the product has to come first. Use data cross products to discover new audience members.

Mayer: Yes, I agree, a unified audience database across a portfolio of magazines opens opportunities cross-line. You can use the information for audience development. The use of the questionnaire to qualify names can yield deeper information than a consumer magazine might have. It can be used to enrich the story we are telling about our audience. We can create new products around it, and products for more vertical segments of the audience.

Fuchs: At HGTV, we do have a huge trust factor that enables us to collect that kind of information from our list. But because of that trust we have to be careful. We use it to leverage more print ads, doing deals, for example, in the fashion space—we don’t have the editorial content, but we have the readers, and we can separate out the audience with that interest for the advertiser. The ads have a high CPM but deliver a very targeted reader who gets a special offer geared specifically for her. We can deliver the value without betraying the trust.

French: People will give information if they trust the brand. Treat them with care.

Elliott: And how does this tie into your approach to native advertising?

Fuchs: Those kinds of collaborations are a quarter of our ad business. We can do it, we have the resources to create it—our advertisers can’t always. Done effectively and with the consumer in mind it has a tremendous revenue potential.

Mayer: Yes, we work with our advertisers to create custom ads through our marketing department. We’ve taken it far enough to create a whole custom publication. It takes a special kind of client relationship. You need to protect the integrity of the brand, and there needs to be a real purpose, a story to tell. We can show the advertiser where that story lies. They might be so close to it that they don’t see their leadership position in their industry. We can help them tell that story.

French: This can fall down at the sales point. It takes really smart people to convey that, delineate what is the content and what is the ad point. I wonder why it’s taken off the way it has, and I think information flow online is not always real or useful, and the reader has learned to be their own traffic cop. Their attitude is, end it to me and I’ll decide what’s useful. As a result, they don’t worry about that particular advertising approach.

Fuchs: Advertising integration is prolific in TV, and online. Print is held to a higher standard, so it is questioned more vigorously. Custom content for an advertiser tends to perform better than the ads the advertiser sends. We can add that value through the trust that we’ve built with our audience..

BoSacks (from the audience): Is there a potential to abuse that trust?

Mayer: Absolutely. The desperation of some publishers might mean they will take a check for anything. It takes a sophisticated sales person to clarify what is or is not possible and acceptable in this kind of relationship. In some ways it’s old wine in new bottles. We’ve always done some of this. But now ad agencies also are being challenged, and getting into content creation for their clients. They can’t always create the content as successfully as the publisher, however, or as appropriately for the publication.

Fuchs: Generating content for the sake of reach compromises brand equity.

French: We have to convey that we are able to help the advertiser re-shape the message to give the audience.

Elliott: Communication and listening need to be part of the skill set.

French: What did you say? (Laughter)

Elliott: You have to train the sales person, to play the client, play the editor, you need someone versatile in listening to put a deal together. This is a big audacious area for publishing.

Fuchs: You learn and make mistakes as you set expectations. Adopt standards, this is what you can get, what you can say, this is what you can’t do. The advertiser doesn’t get final approval, they need to trust that the publisher will execute the ad to the best of their standards.

Elliott: Going into digital: is programmatic a race to the top or a race to the bottom? Or different races?

Mayer: We don’t’ see much on the programmatic front, it delivers an unbelievably low cost per thousand and the ads often look wrong when they run.

Elliott: Publishers put magazines down. TV people don’t do that!

Fuchs: HDTV magazine is about the success of print, a proof point that people want certain types of content in ink on paper. We embrace the idea that there is other media out there and that print serves a very specific role within it. It’s a challenging idea for the television industry as well as the print—not in terms of content, but in terms of platform. The medium influences the message.

French: Some of the most successful brands of the last 10 years are a combination of magazine and TV.

Elliott: What other assets might a media company have?

Mayer: The other assets had better be just as good, must serve a purpose. Your brand must stand for something. This is a golden age of media, but it’s fragmented, vertical. Highest TV viewership has maybe 8% of the audience. Not like when everyone watched the Ed Sullivan show. You have to start with the why. Why do you exist, what is your purpose? Your purpose, your mission, is what connects publishers, advertisers, and audience. If you undersantd your purpose and mission, it brings you forward.

Elliott: What keeps you up at night?

Fuchs: I’m optimistic about the magazine and the business, and optimism is infectious. We’re all excited about the business, and my goal is to lead everyone on my team to that same level of enthusiasm. I think about how to get that level of excitement across the entire organization.

French: My current job is to be an advisor, so I’m brought in to help with transition. Transition is another word for stress. But as someone who is not the operator anymore, I get to advise and be done. My personal challenge is to be at the constant forefront of technology advancement.

Mayer: I try to instill in my team a passion, which becomes almost a righteous indignation if someone says no. We have a cause. The thing that concerns me about tech is the tendency of everyone to get enamored of the shiny new object. We encounter every day people who think the world has moved on, when in a lot of ways it hasn’t.

Elliott: I am concerned over clients who have good ideas, but not the capacity to implement them. Pick a couple of good ones, and know you can execute on them.

h1

Reed Phillips – CEO & Managing Partner, DeSilva+Phillips, Explains How To Add Value To Your Brand Before You Sell It…Linda Ruth Reporting From ACT 7 Experience…

May 1, 2017

Magazines today are not worth what they once were. This is a simple, cold, hard fact based on magazine valuations, whose high-water mark was between 1985 and 2007. This has been followed by a steep decline due to many factors: the growth of internet brands, the disruption of the business model, and the recession of 2008. Reed Phillips, CEO & Managing Partner of DeSilva+Phillips, investment bankers, joined the Magazine Innovation Center’s Act 7 to talk about the consequences of this devaluation and what publishers can do about it.

Phillips has been, for the past 26 years, an investment banker specializing in magazines. Before that he was a magazine publisher himself. It makes him uniquely suited to conduct the roughly 300 transactions, valued at $11 billion, that he has conducted over those years. Selling magazines is what he does.

Business Week, Phillips said, walking the audience through the new landscape of media sales, sold to Bloomberg in 2009 for less than $5 million; 10 years earlier it had rejected a $1 billion offer. Today, Time Inc. is worth less than Vice Media—it has a market cap of $3.2 billion with lower buyer interest, where Vice has been valued at $4 billion. Active Interest Media, going on the block, sold their events, but failed to sell their magazines.

Investors, Phillips explained, are no longer attracted to magazines. They are, skeptical of ad revenues, and they prefer predictable cash flows like software and data centers. Likewise, media companies are reluctant to acquire more magazines, which they see as a drag on their valuations. Today magazines are valued at 4 to 6 times EBITA, roughly half of what they were ten years ago.

Naturally, this makes it harder to sell a magazine. There are things that a publisher can do to improve the prospects for a sale, however. Just as you’d dress up a house before putting it on the market, it’s important to dress up your business, starting the process about a year ahead of time. Use your assets to make the product look less like a magazine, more like a media company, of which the magazine is only one part. Offer potential buyers a company with revenues less dependent on advertising, product lines showing growth to offset magazine declines; and the creation of new businesses from the magazine’s assets. In short, the magazine shouldn’t be the main attraction in the sale, it’s a spoke on the wheel, around a customer-centric hub.

A company without existing litigation, whose owners are in agreement about the sale, whose management team is willing or contractually obligated to stay in place, whose product, both online and offline have been refreshed and updated, whose physical offices also have been refreshed, is more likely to find a buyer.

To ensure success, get expert help from an investment banker and, lawyers. Screen them: have they done similar deals? And remember this: it’s up to you to create the value now and offer it as part of the sale. If you don’t do it, and cash in on it, the buyer will do it afterwards.

h1

A Pre-ACT 7 Experience From Germany and The United Kingdom… Linda Ruth Reporting

April 28, 2017

Linda Ruth reporting with David Atkins and Helmut Graf at the Magazine Innovation Center at Ole Miss.

It’s Day 1 of Dr. Samir Husni’s ACT 7, and people are gathering from around the world to hear what is new in magazine publishing.

I spent an hour this morning with Dr. Husni and two attendees who’d flown in for the event: from Germany, Helmut Graf, CEO of VNR for German Business, Inc., and from England, David Atkins, owner, Newsstand.co U.K.

Helmut and David have weathered many of the same changes in magazine publishing that we’ve experienced in the U.S., and in the process re-defined their businesses. “We began with loose-leaf information binders, a market niche that was taken over by the internet. Today our company focuses on newsletters, and with 300 niche publications covering business-to-business and business-to-consumer, and an average circulation between 300 to 10,000, we have probably 80% of the newsletter business in Germany,” Helmut Graf said. “Years ago, when we were a small entrepreneurial company addressing the business sector, we didn’t have the funding for newsstand, so we tried a different approach. And our success took us by surprise.” The success began, he believes, as a result of a focus on the audience. “Too many publishers begin with a focus on format: a newsletter, a consumer magazine, an online magazine. Each format has its own rules how to do it, its own approaches how to publish. Instead, we focus first on the audience to determine what their needs are; and from there we decide how to address them. The concern with the formats, with the competition, those concerns come after.”

As a result, at a time when the major business magazines on the newsstand have shrunk in distribution from an average of about 100,000 copies to closer to 15,000 each, VNR continues to grow. “We do dozens of newsletters for private investors in Germany, we look at the interests of the investors and we tailor our editorial to meet those needs.”

David Atkins’ business also took an unexpected turn because of changes in the magazine industry, and also found its success in a customer-focused approach. His company began as a wholesale agency, and with the shakeup of the industry and the consequent loss of many businesses, Newsstand.co refocused based on what the customer needed. “We asked ourselves, who was our customer?” Atkins said. “And we replied: it’s the publisher. What does the publisher need; what can we do to enable our publishers’ success?”

The answer, they found, was to help the publishers find their way into the hands of the reader, either direct, through internet sales, or to the shops through online orders. That business model is strengthened and supported by their online strategy. “We used to send an email 3-4 times a year,” Atkins said. “Then we started sending out covers, and our readers really liked that. We don’t include a lot of copy, we let the image speak. Now we send them out daily, and our sales reflect it.”

Newsstand.co provides concierge service: if someone requests or purchases a magazine with a particular person, place or topic, Newsstand.co will follow up to offer another product with the same focus of interest. This approach can lead to a conversion rate of 20% or more. “Our industry needs a way of cross selling magazines, and in so doing, promoting the industry as a whole,” Atkins said. “This is a step towards doing that.”

h1

Sappi’s Daniel Dejan: Presenting The Neuroscience Of Touch. Linda Ruth Reporting From ACT 7 Experience

April 28, 2017

It’s Wednesday, the first morning of ACT 7, the Magazine Innovation Center’s annual opportunity for magazine supply channel partners to come together and learn and share and create. Dr. Samir Husni, the MIC’s founder, kicks off the program by sharing a question that he asked his nine-year-old grandson: which do you like better—the iPad or books? And the response from the child: why do I have to choose?

Out of the mouths of children. For this digital native generation, it’s all there: mobile and digital, broadcast and print, a world of content offering immersion and engagement. And as an indispensable part, magazines. Because, as Dr. Husni says, “As long as we have human beings, we are going to have print.”

Daniel Dejan, the North American Print and Creative Manager.for Sappi, leads off with a deep dive into a fascinating topic: the neuroscience of touch. Sappi, a multi billion dollar paper manufacturer, launched studies on this topic several years ago, when they noticed a disconnect between the perception of print as dead or dying and their own experience as a growing, thriving paper company. They asked the question: is content just content, or is the way that content is delivered also important in some way, physiologically or psychologically? And so they began their research on how people read and process information on different platforms: print, digital, and auditory. In the study, people were given content to consume, and various ways to consume it. And they were measured: their bran scans, their subjective responses, their engagement and their recall.

What they learned was remarkable. A key finding was that with the experience of ink on paper, four of the five senses were stimulated: sight, touch, and, as nuances, smell and sound. People hear the sound of the rustle of paper in ways hard to duplicate digitally; on an olfactory level they know the difference between the smell of newsprint, books, glossy magazines. The experience of reading through each additional sense adds to the level of reader engagement. And, on a wholly practical level, the more the senses are thus stimulated, the more the sense of value goes up, along with the publication’s subsequent sales, with an increase of as much as 18%.

Of course publishers work to create the best possible reading experience digitally as well, using contrast, fonts, color, and also sound, to try to duplicate the auditory experience of turning pages. But what they find, for the most part, is that digital only stimulates one sense, optical. Online remains 80% visual, 20% audio. As a result, the mnemic retention is much longer for ink on paper.

Dejan then introduced the concept, introduced in the book Proust and the Squid, of bilateral literacy. It posits two very different ways of encountering and absorbing content. Readers of print tend to settle in, to absorb the content, to retain more of what they read. On a device, we are barraged with a tsunami of content; and the haptic nature of the device itself is monolithic; once it is familiar, it doesn’t change as the content changes. This makes the aspect of learning that has to do with mapping the information visually in the memory, and being able to recall the very page and position on the page where the information was encountered, very difficult. Because of the content overload, we’ve trained ourselves to become skimmers. The minute we pick up a device, we know we have to get through the quantity. Both ways of gaining information have their role, but from the publisher’s perspective it’s important to design for print differently from online. We know that the online reader is skimming, we want to create design to optimize that speedy experience through the use of bullet, lists, and call outs.

Dejan spoke about the work of Dr. David Ealeman, co-author of Haptic Brain. Haptics is the science of touch, which is, in humans, more remarkable than we are probably aware. A human can detect, on an otherwise smooth surface, a bump 3/100ths of the width of a human hair; and while we do not lead the animal kingdom in our other senses, we are the top species in haptic sense. We use it hugely in non-verbal communication. It helps form our relationships with people. More than half of the brain is devoted to processing the sensory experience, and much of that sensory receptivity focuses on touch.

Ealeman speaks of the Endowment Effect and its relation to the sense of touch. The Endowment Effect has to do with one of the core emotions of humans: desire. Desire’s twin is valuation; we perceive something as having value and hence we desire it. The Endowment Effect is at the core of all marketing and advertising; the goal of such promotion is the ability to create a sense of value and thus trigger desire.

Ownership, or endowment, is a big part of valuation and desire. If I own something, I see it as valuable; more valuable than if you own it. Essentially, things are more valuable if they already belong to us. If you are walking through a store and someone puts something into your hand, it triggers the Endowment Effect. Even just imagining owning something can trigger it, so much of advertising has to do with triggering that mental image. When you own something, you hate to give it up.

And this is what links us back to our haptic brain. Haptic has to do with the sense of touch, and the sense of touch triggers that sense of ownership. This sense can be triggered by holding and shopping on a tablet in a store; it is also triggered by magazine and catalog advertising. When catalog retailers found that so many of their sales took place online, they began to cut back on printing and shipping their catalogs and the results were remarkable; taking out the catalog caused online sales to drop precipitously. Many people, it turns out, start with the catalog then go online to buy. Paper catalogs can drive sales because having the catalog can trigger ownership imagery, wherein touching the catalog becomes a surrogate for touching the object itself.

As the driving force of integrated marketing, technology has brought access to on-demand and real time. Large companies are able to play to this: you want faster and more, we can do this through tech. In a culture that expects and demands immediate gratification, 70% of online orders derive from the physical. So the paper stimulates the Endowment Effect, causing the desire, and the online is able to satisfy the desire by delivering its fulfillment quickly. The stimulus comes from the paper, the action from online.

Magazines can take advantage of this dynamic through their e-commerce storefronts to deliver on desire stimulated by the physical publication.

“Over 100 published studies show people prefer reading on paper,” Dejan told the group. “It is more intuitively navigable, so people enjoy it more and remember it better. Stress is higher when reading online. And the quality of the paper plays into it. A company using higher paper is viewed as more trustworthy, and people coming into contact with its product were more likely to recommend it as opposed to readers exposed to the product through thinner paper or online. A week after the original exposure to the company product, the companies originally encountered through a high quality paper still enjoyed, 3 to 1, a more favorable impression and were better recollected. The lower quality paper left people with more doubts about the company and the product. The physical nature of paper unconsciously influences our decisions.

“As a result,” Dejan continued, “the magazines doing extraordinarily well print better, use better paper, do special sizing, and create an overall positive experience.”

He wound up his presentation with Riepl’s Law, which summarizes: New further developed types of media never replace the existing modes…a convergence takes place leading to a different way and field of use for older forms.

According to Riepl, then, newer media will not replace older media, but instead take its place alongside existing media and help create changes in the media experience itself. A new law? Not really. Riepl created this one in 1913.