Archive for the ‘News and Views’ Category

h1

A New Conversation With Consumers: The Revamping Of Consumer Reports. The Mr. Magazine™ Interview With Editor, Ellen Kampinsky & VP General Manager, Brent Diamond.

October 16, 2014

“A lot of the changes were designed to do two things: create a contemporary magazine, because readers are used to getting their information from a variety of media, particularly from contemporary, sophisticated magazines and we wanted to make our mission very obvious and clear.” Ellen Kampinsky
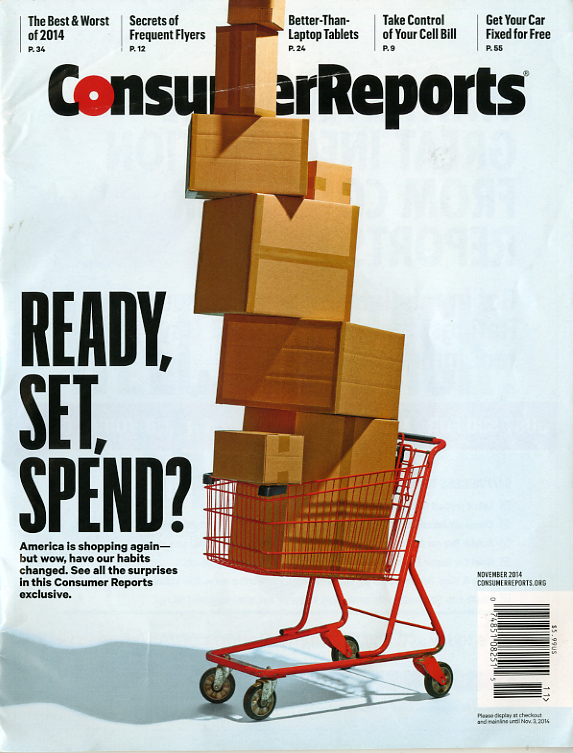
Consumer Reports-1 There is one rule of thumb for most any board game played; you have to roll the dice if you plan on moving around the board to win. Sometimes in the world of magazine media, the rules aren’t any different.

Since 1936 Consumer Reports magazine has been the most trusted source for reviews and comparisons of consumer products and reports from in-house laboratory testing in the world. But with the November 2014 issue, some things are changing, in fact a lot of things are changing, however the mission and focus of the magazine are not changing. Looking out for the consumer hasn’t changed nor will it change, according to Brent Diamond and Ellen Kampinsky, two of the driving forces behind the powerhouse magazine.

But is this the biggest gamble in the history of the magazine? Have they rolled the dice too hard with the revamp of a trusted brand with loyal and committed customers? And is having feature stories in a magazine that usually reports statistics, lists and reviews something the audience can relate to?

I went to Ellen Kampinsky, Editor, and Brent Diamond, VP General Manager, to find out the answer to those questions and many more about the “new & improved” Consumer Reports. I think you’ll find their answers very enlightening.

So sit back and enjoy the Mr. Magazine™ conversation with Ellen and Brent and learn how a 78-year-old brand can be reborn into the 21st century.

But first the sound-bites:


On the reasons for the change:
Really the impetus for the revamp was to create a much more relevant and deeper engagement with our readers and secondly to highlight all the great things that we do on behalf of consumers.

On the reaction to the November issue (the first new edition released Sept. 30) from the magazine’s readers and others:
Yes, we’ve gotten more feedback than we anticipated. Both positive, and there have been some detractors; change can be hard for people, these are very, very loyal, long-term subscribers. So, we’ve gotten a lot of both types of reactions.

On whether they went too far or this change was needed:
A lot of the changes were designed to do two things: create a contemporary magazine, because readers are used to getting their information from a variety of media, particularly from contemporary, sophisticated magazines and we wanted to make our mission very obvious and clear.

On the magazine’s “Advocate” section:
Part of the role of an advocate section is to be involved in a dialogue with the readers. It’s there for them and a lot of the information in that section is generated by them.

On whether they’re worried the revamp will shrink or obliterate the magazine’s original DNA:
The part of our DNA that will likely never change is that what we really offer that other magazines don’t is tested, unbiased information for consumers.

On why their “no advertising accepted” business model works for them:
There are people, as much today as ever before, who will pay for valuable information that helps them make smarter and better decisions.

On whether they ever envision a day when Consumer Reports will be digital-only with no print edition:
I can foresee delivering the product in various and different ways, but I don’t think the mission and the core of what we do will ever change, whether there continues to be a magazine 20 years from now or not. I don’t know.

On whether more book-a-zine type products are on the horizon:
Where we start from all the time is a need in the marketplace or a need that consumers have and if there’s a need there, we’ll try and find a way to fill it.

On what keeps them up at night:
This is not a cliché, but what keeps me up at night is the thought of not evolving and not changing quick enough to match how consumers are consuming information today. (Brent Diamond)

And now the lightly edited transcript of the Mr. Magazine™ interview with Ellen Kampinsky, Editor, and Brent Diamond, VP General Manager, Consumer Reports…

Samir Husni: Congratulations on the revamping of the magazine. And I know that it’s much more than just a redesign. Can you tell me why you decided now was the time for this and the reasoning behind the change?
Usage: Story: Brand: Model: Brent Diamond CU: Photographer: John Walsh Brent Diamond: I don’t know if you recall, but well over a year ago I had a brief conversation with you and that was just as we were exploring and really trying to decide where to go.

So what we have done is a fairly in depth analyses of our business and in the end a couple of things were highlighted: our subscriber base was pretty flat for the past six years. For every new subscriber that we brought in, we were losing a subscriber, so we were just maintaining and going along status quo.

Really the impetus for the revamp was to create a much more relevant and deeper engagement with our readers and secondly to highlight all the great things that we do on behalf of consumers. And we felt that if we combined those two things we could have a much more meaningful relationship with our customers and therefore we could find more customers and keep them. In a nutshell, that’s what we’re trying to do.

Samir Husni: I know the new issue has only been on the newsstand for a few days; what has been the reaction? Have you been bombarded with people sending you emails crying, “What have you done?” or have you been hearing the opposite, “Wow! We love it?”

Brent Diamond: One thing you should know is that newsstand is only about 7 % of our base of customers. And while that’s an important piece of our business, we’re more worried about the subscriber base. And yes, we’ve gotten more feedback than we anticipated. Both positive, and there have been some detractors; change can be hard for people, these are very, very loyal, long-term subscribers. So, we’ve gotten a lot of both types of reactions.

What we’ve done is invited the people who have expressed both the positive and the negative comments to join our advisory panel to help us to continue to shape and evolve the magazine.

Samir Husni: Ellen, as the editor it’s as though you’re taking this enormous cruise ship and trying to make a turn on a dime; do you think you’ve gone too far with the first issue or do you think you needed to make this drastic change?
Ellen Kampinsky Ellen Kampinsky: I think the magazine needed a couple of things to make it a successful, contemporary magazine. It needed some reorganization of the sections so that it was clear what the readers were seeing. We needed to highlight our mission; we added features that tell readers that we are working for them and tells them how they can get involved and be empowered. Some of these things are absolutely necessary I think, because we do something that no one else does; we’re there for the reader, not for advertisers, and I think it was really important to make that manifest. A lot of the changes were designed to do two things: create a contemporary magazine, because readers are used to getting their information from a variety of media, particularly from contemporary, sophisticated magazines and we wanted to make our mission very obvious and clear.

Samir Husni: And I noticed you’ve added an “Advocate” section to the magazine. So, are you going to be more involved than ever? The magazine has always had an advocacy role and a very consumer centric approach; how do you envision this new section adding to that existing role? Specifically because you’ve never had advertising and I doubt that you ever will and yet, you are one of the largest magazines in the industry.

Ellen Kampinsky: Part of the role of an advocate section is to be involved in a dialogue with the readers. It’s there for them and a lot of the information in that section is generated by them. And we get the intake on that, not just from the magazine, but also online and we recognize the reader is part of the media spectrum, so we ask them descending questions for the “Problem Solver” or “Ask Our Expert” and we ask them to get involved by signing a petition or by writing their congressperson or going online. We ask them to send in reader tips, either by mail or online and for the best reader tip we’ll pay them $100.

We just want this constant dialogue going on, this constant two-way street with the reader and that’s what the “Advocate” section is all about.

Samir Husni: Do you think that there’s a danger that you may have went too far and Consumer Reports is now competing with other magazines that focus on a single-topic cover story? I mean, do you feel that now the magazine is more in sync with the rest of the magazines that are available to the consumer? And how are you going to protect your DNA, which are the tests and the rankings that you offer your readers?

Brent Diamond: I think that particular issue (the first new issue) had fewer products in it than we normally have, that happened to be a fairly issue-oriented month for us and so while it might appear that we went a little too far, it was just the editorial make-up of that given month. I think you’ll see in the next issue that it’s much more heavily product-focused.

But the part of our DNA that will likely never change is that what we really offer that other magazines don’t is tested, unbiased information for consumers. So we have no problem telling you that this is a great product and you should buy it. On the other hand, we don’t have an issue with saying this really isn’t a great product and you should avoid it. And that will remain a very key component in what we do. And there is nobody else that does that.

Ellen Kampinsky: And the ratings will always be a part of our core product, the ratings and the listings. I mean, it’s a combination of product and services. And you’ll see a lot of that in the December issue.

Samir Husni: You are one of the few magazines left in the country that doesn’t accept advertising, not that you couldn’t get it, but you don’t take the advertising. Do you think this is a sustainable business model for 2014 and the future? And if so, why do you think other publishing houses aren’t going in your direction; you charge a hefty subscription price and you charge for your digital; why do you think it’s working for you and you’re unique?

Brent Diamond: There are people, as much today as ever before, who will pay for valuable information that helps them make smarter and better decisions. I can’t speak for why other publishers don’t do it, but for us it’s always going to be a value proposition for the reader, which really goes back to why we did all of this. We have to remain invaluable to all of these readers because that is our business and our revenue model. So the deeper we’re engaged with them, the more meaningful discussions we have with them, the more we’ve become a critical part of their lives, to the point where they don’t make big decisions without working with us.

And that’s what makes us different. I don’t know of another magazine or media company that really does that.

Samir Husni: Ellen, as an editor of a magazine that has no advertising; do you feel like you’re on cloud nine? Do you feel your responsibility is more or less?

Ellen Kampinsky: (Laughs) I absolutely do feel like I’m on cloud nine. It’s so terrific to be able to call a spade a spade, this works, this doesn’t work. It’s freeing and it makes you appreciate what journalism can do at its best.

Samir Husni: If the November issue is an indication of the future; where do you think the point of differentiation will be between Consumer Reports in 2015 and Consumer Reports before then?

Ellen Kampinsky: I think taking into account the people who consume their information in various ways, that the visuals are as much a part of the information as the text, they work hand-in-hand, recognizing how smart our readers are, how varied their lives are, and then I think it’s just cranking it up another notch to create the ultimate, ultimate service magazine; we’re already in first place there anyway, but then taking it up to the next level of service.

Samir Husni: You are doing all of these changes, but I read one of your comments where you said that you would never put one of the Kardashians on the cover. (Laughs)

Ellen Kampinsky: (Also laughs) Are you asking am I planning to change that? Maybe Justin Bieber? No, I don’t think so.

Samir Husni: You’re investing a lot of money in the revamp of the print edition, but do you ever envision a day when Consumer Reports will be only online or digital?

Brent Diamond: I don’t know. I think the way we all consume media is continually changing, but will there be a day when you don’t get a print edition of Consumer Reports? I can foresee delivering the product in various and different ways, but I don’t think the mission and the core of what we do will ever change, whether there continues to be a magazine 20 years from now or not. I don’t know. As long as people continue to want to consume media that way, we’ll continue doing it. But I believe the point is, we’ll evolve with our readers and the way they consume information.

Samir Husni: Ellen, do you think it would be different editing a magazine that does not have a print edition from an editorial point of view, one that is digital-only?

Ellen Kampinsky: Yes, it would. I think there is always going to be a role for print and that’s what we’re trying to do, evolve our print edition in concert with all our other products online and offline, into the highest form possible. I mean, we look at the graphics as one of our multiple entry points, we look at different ways to engage the reader and I think that’s our job right now, finding all those entry points and all those engagement points for them, that makes the print magazine being in concert with everything else we’re doing absolutely essential.

Samir Husni: Brent, I noticed you’re adding to the roster of special editions and SIP’s, having just launched the Reliability Guide; are we going to see more spinoffs along the lines of book-a-zines and the SIPs on the newsstands, from Consumer Reports?

Brent Diamond: What we always look for are our needs for information, so an SIP and a magazine is only one way of distributing that kind of information. But I think what we’re trying to do is give consumers information in the way that they want to consume it. Rather than us make the judgment as to how people should consume it, we’re kind of letting them decide.

Where we start from all the time is a need in the marketplace or a need that consumers have and if there’s a need there, we’ll try and find a way to fill it.

Samir Husni: Is there anything else you’d like to add or focus on that we haven’t discussed yet?

Brent Diamond: Well, I believe what is really key here is that by involving the consumer so heavily, we, in theory, should never have to go through a major revamp again, because if we do this right and we are having an ongoing dialogue with our customers, we should be able to evolve and change based on their input and their usage of what we’re doing. I think that’s a key component of what we’re trying to do, involve them in the process and not just be the spreader-of-all-wisdom; we’re trying to involve them in this process.

Ellen Kampinsky: I think a key point that Brent made is, OK – we’ve revamped the magazine, let’s sit back, we’re done now. No. This will continue to evolve as the readers respond, as we seek new ways to make it better and better. And that’s almost as exciting as not having any advertising. (Laughs) Almost, but not quite. (Laughs again)

Samir Husni: My typical last question; what keeps you both up at night?

Ellen Kampinsky: What keeps me up at night? Well, there’s always another issue to put out. I think any editor would say the next issue always keeps you up at night. Is it going to be the best, are we going to make the deadlines and is it being done to the very highest degree that we can.

Brent Diamond: This is not a cliché, but what keeps me up at night is the thought of not evolving and not changing quick enough to match how consumers are consuming information today. I worry about that all of the time. We have to continually evolve and change to help them make better decisions. That’s key.

Samir Husni: Thank you.

h1

Magazine Service Journalism At Its Best: Dana Points, Content Director, Meredith Parents Network. An ACT 5 Experience Presentation

October 15, 2014

Dana Points, content director of Meredith Parents Network, was the opening keynote speaker of day three (Oct. 9) of the Magazine Innovation Center’s ACT 5 Experience. Click below to view her presentation.

h1

The Future of Digital Starts With Print; Or Does It? Keith Bellows’ ACT 5 Presentation

October 14, 2014

Keith Bellows, EVP/Editor-in-Chief of National Geographic Traveler and Travel Media ended day two of presentations at the ACT 5 Experience on Oct. 8. Click below to watch his presentation.

h1

Single Copy Sales: A View from Norway. An ACT 5 Experience Presentation.

October 14, 2014

Espen Tollefsen, CEO of Interpress, Norway, presented a view from Norway on single copy sales and distribution. His presentation took place on Oct. 8 at the ACT 5 Experience at The University of Mississippi’s Magazine Innovation Center. Click on the video below to watch his presentation.

h1

Magazine Covers and The Single Copy Sales: A MagNet ACT 5 Experience Presentation

October 14, 2014

Gil Brechtel, president of MagNet, and Joshua Gary of MagNet presented the MagNet latest research on covers and single copy sales. Click below to watch their presentation on Oct. 8 at the ACT 5 Experience.

h1

Building and Managing Magazine and Magazine Media Audiences: An ACT 5 Experience Presentation

October 14, 2014

John Harrington, publisher of The New Single Copy newsletter and a member of the advisory board of the Magazine Innovation Center @ The University of Mississippi moderated a panel discussion on Oct. 8 during the ACT 5 Experience. His guests were Malcolm Netburn, CDS Global, and John Phelan, Rodale. Click below to watch the panel discussion.

h1

The Future Of Publishing Is Found In Its Youth: Reflections on ACT 5 Experience

October 14, 2014

From the Foredeck of the Titanic
by Joe Berger

I vividly remember my reaction to Dr. Samir Husni’s announcement that he was forming the Magazine Innovation Center at Ole Miss University. It was the winter of 2009. The economy was deep into a slump. The smoldering wreckage of Anderson News was still wreaking havoc on newsstand distribution. It seemed like every day there was another article in the industry trades about the death of print magazines. The web was full of snark and Schadenfreude and the Reaper at Magazine Death Pool was getting more coverage than most writers who covered the magazine world.

Dr. Husni had an interesting response to this roiling mess. Thoroughly fed up with the news that another magazine was shutting down, he announced that he was fighting back. The Magazine Innovation Center at the University of Mississippi was going to be a place where publishers could re-imagine, amplify, clarify and testify to the future of print.

screen-shot-2014-10-13-at-8-56-37-am

I don’t think anyone would ever say that Samir Husni isn’t bold. My reaction that day was a fist pump, and loud “Yes!” that startled the cat.

A year and a half later, after a job transition, several client changes, and more non-stop bad news in the industry trades, I made my way down to Oxford, MS for the very first ACT I conference. Two thoughts crossed my mind as I looked at the agenda during the first full day of the conference:

“I had never attended a publishing conference that wasn’t thoroughly dominated by the largest magazine companies in the industry.”

And “I had no idea that so many students still wanted to go into magazine publishing.”

Over the next three days, an Ole Miss student and a young startup publisher and me swapped notes, ideas, advice and hope while we listened to a panel of speakers that included consumer, B2B, custom and foreign publishers. We learned about the potential, promise and pitfalls of digital publishing. We learned that in the world of print publishing, the future didn’t have to be an early grave and a post in the Reaper’s Blog if we were nimble, willing to change, willing to work hard and produce quality publications.

That was the best feature of the conference. Not that the speakers weren’t excellent. They were. Not that the speakers spoke about a diverse series of topics ranging from custom publishing, digital editions, social media and e-commerce. They did. But for the first time in a long time, I was able to interact with the next generation of magazine publishers and it was revitalizing to see how committed they were to their career paths.

screen-shot-2014-10-13-at-8-55-57-am

Last week I landed in Oxford again for ACT V. ACT stands for “Amplify, Clarify and Testify” and there were surely plenty of speakers who attested to that fact. The keynote address was from Michael Clinton of Hearst who gave a good case for how and why Hearst’s print magazines and their digital cousins co-exist and mean so much to each other.

But the next day, it was the students who responded enthusiastically to the presentation by Vanessa Bush, the eloquent and engaging editor of Essence Magazine.* Billy Morris, the CEO of Morris Communications connected the dots between magazine publishing and the need for continued journalistic integrity. Greg Sullivan, one of the founders of the successful startup Afar Magazine, kept the audience spellbound with his description of how the magazine got started and all of the other avenues, many digital, that the magazine has taken the publishing company into.

For me the experience was much like going back to college. And sitting next to the schools undergraduate and graduate journalism students reminded of how important it is for our business to recruit the talented, the dedicated, the enthusiastic, the committed. A few snarky comments written by a reporter who’s never spent five minutes understanding the intersection between social media and circulation shouldn’t control the future of magazine publishing. Clearly these kids don’t think so.

If the future of our industry lies in the hands of the four talented, engaging, thoughtful and interesting women and men who joined me for dinner last Thursday night, our business has nothing to fear and nowhere to go but up.

This week, it’s back to work. It’s back to the grind of airlines, presentations, galleys, reports and Account Executives. That’s fine. I’m armed with a bevy of information, hope and excitement for the future.

*Note: Essence Magazine is the creator of the Essence Festival, a live event the magazine hosts each year. The Festival features performers, speakers and a wide range of activities that attracts African American families from all over the country. This year, the event was hosted in New Orleans and attracted over 500,000 participants. That’s larger than ComicCon, Coachella, South By Southwest and Sundance. Considering that this event doesn’t get mainstream media buzz, can anyone wonder or deny the power of branded magazine publishing?

h1

The Magic and Marvel of the ACT Experience: BoSacks Speaks Out.

October 13, 2014

By Bo Sacks

BoSacks Speaks Out: On Hearst, Mt. Olympus, Oxford and Great Publishing Conferences

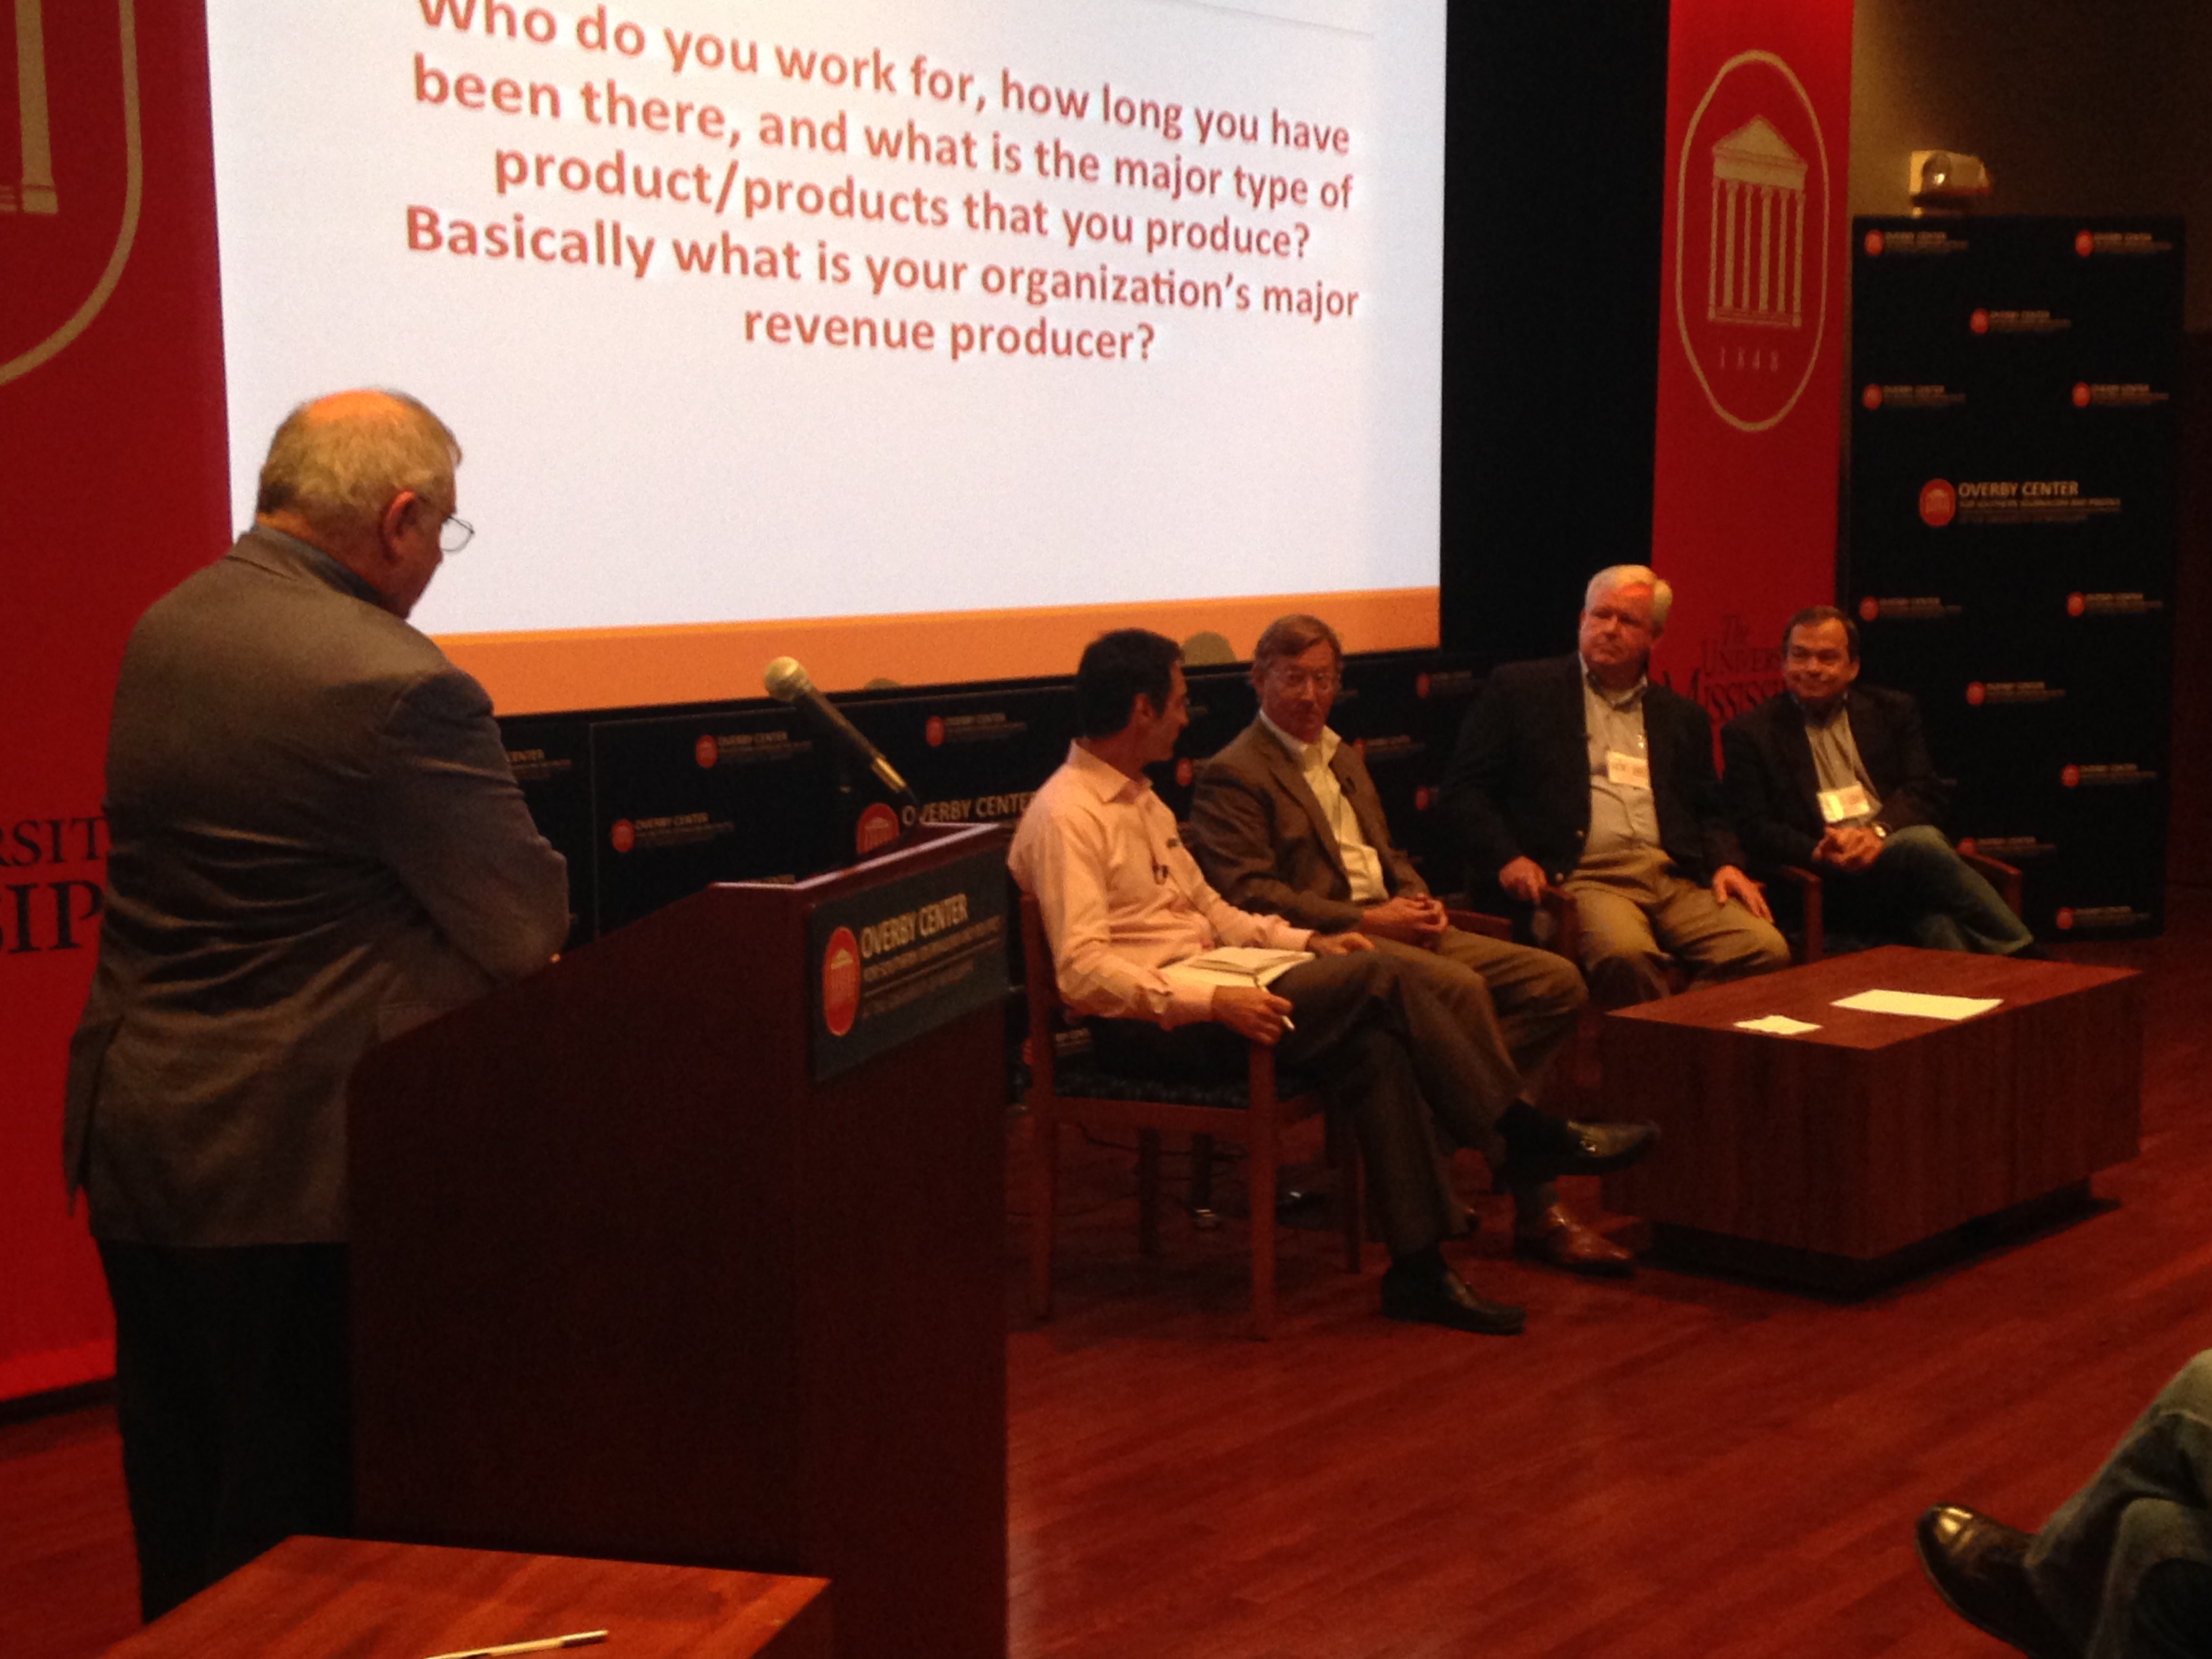
IMG_6708 You would think that a guy who goes to a dozen publishing conferences a year and is also the writer/publisher of a daily newsletter on the subject of media, would find it easy to explain why the annual ACT magazine events at the University of Mississippi are so compelling. My problem is that it is hard to exactly define magic, and this special event is filled with magic and marvel. It is hosted by my good friend and industry debating partner Professor Samir Husni, who continuously attracts a world-wide concoction of diverse speakers. But it is not exactly the diversity of the presenters that makes it so special. If that was all it took, it would be easy to replicate, but nobody has an event quite like this one.

Perhaps the most unique thing about the conference is the intimacy of the event along with the interchange with the students. As conferences go it is probably the smallest by population, yet the biggest in comradery and geniality. The auditorium is filled with 40 professional speakers and about the same amount of journalism/media students. We are an intentionally mixed group sitting randomly in the journalism school’s cozy auditorium, senior publishing professionals hobnobbing side-by-side with the next and soon to be leaders of the noble enterprise we call media.

As a professional speaker I think that what I like and look forward to the most is the odd blending of presenting simultaneously to professionals and students. It is a special process to be able to mentor the young and eager and the seasoned professional in the same talk. It has to be detailed enough to keep the interest of the professional and exciting enough to entrance the apprentice.

The list of luminaries was impressive. It started with a keynote by Michael Clinton, President, Marketing and Publishing Director of Hearst Magazines. Michael gave a truly passionate account of what Hearst is up to in this age of publishing transformation. He started with the declaration, “Our children and grandchildren will still read print.” He advised us all interestingly enough with the same advice delivered by Brian Hoffman of Hoffman Media two days later, that you should design your covers and content based on what you know your readers want and urged that we get into the “pulse of the zeitgeist” to know what Americans are looking for.

IMG_6717 Michael questioned, “If print is dying, why was the 2014 launch of Hearst’s Dr. Oz, the Good Life such a fantastic success? Its first issue sold out on newsstand and it achieved 300,000 subs in 4 months.” He pointed out that magazine readership has been relatively constant at 187 million, even while there is massive disruption in other mediums such as TV audiences. (I actually disagree with the implied serenity of that conclusion, but my reasoning will have to be discussed in another Bo-essay, at another time.)

Michael went on to familiarize us with Hearst “Unbound” and how magazine brands should now exist on a global scale and on many platforms with social media, you tube videos, websites, mobile applications, tablet editions and narrowed targeted editions; for example, Cosmo for Latinas.

Michael also went into some details about how the size of the audience matters more than the measurement of ad pages, (another conclusion that I reserve the right to explore and discuss at a later date.) He previewed the now available “Magazine Media 360,” which is the MPA’s new measurement tool for capturing how readers are connected to magazines across multiple platforms, and not only the print product. This is a bold attempt to combine total magazine reach, a combination of digital audiences and print circulations.

Michael discussed the many paths that Hearst is traveling down other than their core print products. The list of adventures and undertakings at Hearst is as huge as it is possible to imagine and an outside inspiration for publishers everywhere.

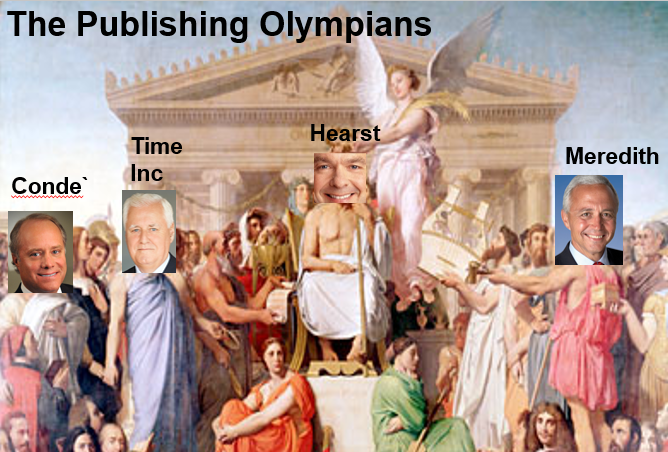
A few days later on in the event, when it was my turn to stand before the audience, I offered the following observations: “We heard from Michael Clinton on Tuesday night. His talk was enthusiastic, and uplifting. Indeed Hearst is doing many wonderful things. But he is from a group of Publishing Olympians. If you have as much money as a Greek god, it makes the transformation of our industry look pretty damn easy. They (Hearst) and the other Olympians, such as Time Inc, Meredith, Conde` Nast, Bonnier and a few others can afford to fail many times without effecting the long-term bottom line.

2561

As wonderful as it is to hear of what is possible in the extreme, there are 9,000 other titles working down here on the planet earth, who oddly enough don’t have Olympian resources and yet some are still doing quite well anyway.

2562

After that observation, I focused my discussion in an attempt to make a case for the students to understand that in the midst of the downward trends of print in today’s market place there still continues to be many success stories. In the next session, when I moderated a panel of printers, including Publisher’s Press, Democrat Printing, and Shweiki Media, they confirmed the same thought and took it a step further. The printers brought to everyone’s attention the many thousands of unaudited titles that exist in their shops and the vitality of free circulation magazines.

A thought worth remembering is that when it comes to counting magazines that are produced, it is the unaudited titles that are in the majority and the audited magazines in the minority. And that ratio is by a very large margin.

There is much more that is worth discussing, but I am writing this on my plane ride home and will have to end my recap here. In the next few days I will attempt to go over the many other highlights of this terrific conference.

Post Script: One part of the conference is the assignment of student “shadows” whose job it is to meet, greet and work with all the professionals for the duration of the event. A special note of thanks to my articulate, hard-working and impressive shadow, Jared L. Boyd, with whom it was a pleasure to work and mentor.

Here are just a few of the people and the notes that I’ll be writing about:

William Morris III (Chairman, Morris Communications):

* We’ve moved from information scarcity to information overload

Vanessa Bush (Editor in Chief, Essence Magazine):

* Print is giving birth to countless abundant opportunities to engage with our audiences

John Harrington (Publisher, The New Single Copy)

Malcolm Netburn (Chairman, CDS Global)

John Phelan (Executive Director Consumer Marketing, Rodale):

* Predictive data is the connective tissue between an issue and its readership

* The distance between content and audience must narrow

* We don’t know how to measure success right now — digital tools and platforms are changing everything

Gil Brechtel (President, MagNet)

Joshua Gary (MagNet):

* There’s turmoil in the newsstand but there can be a predictability to be made from it

* 15% of magazines sold are now bookazines, which are starting to flood the market

Espen Tollefsen (CEO, Interpress, Norway):

* Magazine markets are declining

* International titles are declining as well as domestic titles

* #1 reason for large drop is not mobile — it’s a decline in “in-store” focus and distribution issues

Keith Bellows (EVP, Editor-in-Chief, National Geographic Traveler and Travel Media):

* We’re still in the middle of the bridge between print and digital — still driving “dazed and confused”

* Natl Geo is not a media company — we have only 3 mags — rather it’s all about Natl Geo’s mission to teach people about the planet

* The era of relying on subs and advertising to keep the company profitable is over

* The stories are what drives media — don’t lose sight of that

Roy Reiman (founder, Reiman Publications):

* The Act conference brings together people who are “doers instead of dreamers” who are not afraid to share both their mistakes and their successes

h1

The Passion for Magazines: Vanessa Bush, Editor in Chief, Essence Magazine. An ACT Experience Presentation.

October 13, 2014

Vanessa Bush, editor in chief of Essence magazine, delivered the morning keynote address of day two (October 8) of the ACT 5 Experience at the Magazine Innovation Center @ The University of Mississippi. Click below to watch her presentation.

h1

“Magazine Media 360” Explained. The Mr. Magazine™ Interview With Mary Berner, President & CEO, MPA – The Association of Magazine Media.

October 13, 2014

Capturing Demand For Magazine Media Content By Measuring Audiences Across Multiple Platforms And Formats.

“What this does is make us the first-ever media to capture as an industry, basically the cross-platform demand by brand. No other industry does this.” Mary Berner

Picture 13

Magazine Media 360 is a newly created industry metric that captures demand for magazine media content by measuring audiences across multiple platforms and formats (including print/digital editions, websites and video) to provide a comprehensive and accurate picture of magazine media vitality. Magazine Media 360° uses data from leading third-party providers and from the reader universe. This is the first time ever by any media to measure and communicate cross-platform consumer demand by brand.

Mary Berner, President & CEO, MPA – The Association of Magazine Media, believes in the driving force of this new metric that can measure platforms as a whole, rather than just from the print side.

I reached out to Mary recently and our conversation was focused on the new consumer centric and audience-first mentality Magazine Media 360 promotes and advocates. The time for this type of thinking in the magazine media industry, Berner believes, is one that has finally come and will help to change the reality of the way the industry measures and monetizes the many platforms offered to the consumer today.

So sit back and enjoy the Mr. Magazine™ interview with Mary Berner, President & CEO, MPA.

But first the sound-bites…


berner-mary-mpa_0 On the purpose of Magazine Media 360:
For us as an industry, this is a game changer. What it does is reflect a very seismic shift away from communicating and capturing print-only metrics to a whole ecosystem metric.

On the timing of the new measuring system:
I don’t think the industry was ready for it yet, I think we needed some critical mass in terms of multi-platform distribution content and frankly the third party research providers weren’t yet ready to get the data; so I think the time is right now.

On whether she believes the magazine media industry’s problems have all been self-inflicted:
I would say that print is a part of the consumer consumption experience, an extremely important part, but I would say that we haven’t told the story in regards to consumer demand up to this point.

On the major stumbling blocks she believes will be encountered along the way:
To be truthful, our attention in trying to figure out all the things that could and might go wrong ahead of time and addressing any and all challenges before we actually launched this, puts us in a position where we’ve asked and answered many of the stumbling blocks.

On what’s next for Mary Berner and Magazine Media 360:
This is just the beginning. I think it’s a good first step, but what we need to show is engagements, because we know from research in various companies the engagements in these brands of these multi-platform experiences are really extraordinary.


And now the lightly edited transcription of the Mr. Magazine™ interview with Mary Berner, President & CEO, MPA… Keep in mind, that since this is a brand new tool the MPA is using in measuring the strength of magazines and magazine media I’ve opted for a full explanation and presentation that Mary shared with me. It is essential to document and understand this new milestone marker in the history of magazines and magazine media..


Samir Husni: Explain Magazine Media 360 and the reasons behind this new magazine media measurement plan.

Picture 14
Mary Berner: For us as an industry, this is a game changer. What it does is reflect a very seismic shift away from communicating and capturing print-only metrics to a whole ecosystem metric. And as such when you look at the data, it actually redefines the state of magazine media. We believe that consumer demand also means money.

The idea for this and I believe you and I talked about it and debated it, but essentially the word magazine was the impetus for this entire idea. The word magazine for most people almost always refers to the print product. And yet every company pretty much operates as multi-platform, multimedia companies.

So the impetus was the shift from being magazine companies to magazine media companies and every single one of them does this and this is an interesting concept, so keep this in mind when you think about our methodology. The one thing that’s unique about magazine media and we’re defining it as a content brand that is anchored in a print magazine, but also disseminates magazine media content across many platforms and formats, so the magazine media content strategy is, for the most part, a platform-specific strategy, which means you create the content specific to the platform, as opposed to, for example, a television strategy which is platform agnostic. And that means you have an everywhere, anywhere strategy where the consumer gets the same content wherever they are, whenever they want it.

And by definition the audience augmenting, or differentiating content has actually been audience augmenting, because any one of these experiences, for example on Sunset, you consume as a consumer on its own and you would do so because you understand the Sunset brand means something, whereas the audience fragmented television strategy is audience fragmenting because obviously, you wouldn’t watch the same program again and again.

And this pretty much applies…this kind of platform-specific content strategy, to just about every brand, at least the major ones. So, for example, I could consume the video content from Woman’s World, which for them would be focused on exercise, without ever being a reader of the print version of the magazine media content. And we’re finding that the numbers bear this out, that digital-only consumers are going to the brand experience under the magazine media brand and this applies to just about all of the major magazines.

Essentially, here’s how we got to where we got to; right now what we have is print metrics and with advertising, for example; out of 10 advertisers only two limit their investment in that brand to the print version, only two. Eight of the others also invest across the multiple platforms. So it’s 80% that do something besides print. Yet a PIB (Publishers Information Bureau) or an advertising paging number only captures one part of it and in no way captures an advertiser’s commitment to a brand. So by definition it’s incomplete and therefore inaccurate.

And that played out again and again this fall. For example, the September issue of one of the big fashion magazines had a PIB number that was down, yet their advertising performance was the best it had been in 15 years, because the advertisers committed to multi-platform packages. In isolation, a print advertising page number just isn’t a great metric anymore.

And ditto for circulation if you look at the AAM (Alliance for Audited Media, the former ABC, Audit Bureau of Circulation) statements. Circulation is basically the counting of copies sold or distributed. Yet, if you add up all the AAM titles, they represent only 30% of the total print magazine audience, which is how planners buy. So, it doesn’t really tell the whole story. And then when you actually apply that to the whole ecosystem, the AAM circulation represents only 21% of the total audience. So using a circulation number in isolation, I think it does certain things, but in isolation by definition, it’s like pegging the audience or the vitality of the Super Bowl based on the number of people in the stadium, it essentially under captures.

Picture 14 Yet, in light of all that, what we’ve asked ourselves is what is the common courtesy and how do we measure what’s really going on, because, this is the data we got for July; we did three months of data and essentially what we’re seeing is that the lion’s share of the business is still print and will continue to be so for the foreseeable future, if not forever, but other platforms and formats are gaining scale. And when you look at the whole ecosystem and you leave out those others: video, mobile, web, desktop, laptop and digital; you leave out 35% of the business essentially. And when you look at the total pie, it was up 7.8% overall.

People say that the lion’s share of revenue and profit is in the print publications and I say, yes, that’s absolutely true for now. However, that is rapidly changing. Look at Meredith; Meredith is up to almost 20% of their revenue coming in from digital sources and that’s kind of an old school company. And it’s rapidly growing. The only proxy really for vitality, I would argue, for current health or future promise would be consumer demand. It’s certainly how brands like BuzzFeed are measured. And it’s also the only common currency among all media. In a world where you can’t define what makes television television, consumer demand is an important one.

So, what we did was we created Magazine Media 360 and essentially it’s an attempt to present a comprehensive picture of consumer demand for magazine brands. And in such, it captures print and digital editions; it captures websites, including desktop, laptop, mobile and video. Next, this month we’re going to release a social media report that’s separate, it doesn’t roll up into that because it’s a whole different animal.

What this does is make us the first-ever media to capture as an industry, basically the cross-platform demand by brand. No other industry does this. Television gives Nielsen ratings when they want to; they don’t give them as an industry, they don’t give them by brand and they certainly don’t give any revenue numbers. So, what we’ve done with this is capture that additional 35% which makes this a comprehensive and a consumer centric and really a more accurate barometer, if you will, of a company and an industry’s vitality.

But how do we figure out how to do this? Well, we decided we had to use third party reputable information, otherwise people would game it. You had to qualify it; you had to actually be multi-platform to qualify. So we used very reputable data from Nielsen, comScore and others and we had a very, very rigorous process about how to get the data and what to pull.

What we’ve essentially decided to do after consultations with many, many experts is we’re pulling, not page views, not traffic, but unique visitors and unique viewers and audience numbers. It’s a more conservative number and it gives us a more accurate picture.

So with third party data we’ve covered the whole pie and the story it tells is interesting. We have 95% industry buy-in, which essentially means we had 30 companies to buy-in and that represents 147 brands. We only had three brands not do it that qualified. One was the Shank titles, the other was a tennis magazine, mostly because they just didn’t respond to emails and the other is Wenner, because you have to also be a MPA member to qualify and there are only two major companies that aren’t, Wenner and Bauer, but it didn’t affect the numbers, even with them not in here, it covers 95% of the magazine reader universe and basically represents the entire industry.

The process works with all 147 brands giving their data to us and they pull it from comScore, Nielsen and other reputable companies. We then aggregate the data and post it publicly, so every single month we will post 147 brands and their consumer-demand number by platform and then a total aggregate 360 number. So it’s really an unprecedented model of transparency and it took an enormous amount of courage, if you ask me, from all these publishers. And we at the MPA will show the trends.

For the first one we launched publicly, it was August over August; we do the same period over the same period; what we saw was a 10% growth in total audience and we saw that was coming from mobile web, a lot of mobile web growth. And print, while it’s a smaller part of the pie, was actually up 1.1%, so it’s just a smaller part of a growing pie.

Picture 14 We’ll soon begin social media reports, which we’ll do toward the end of the month and the response was uniformly positive. Most importantly the advertising community and these are three of the biggest buyers representing three of the biggest agencies and every single one of them was applauding because the concept is you can’t sell what you can’t measure; you can’t sell it to a consumer and you can’t sell it to an advertiser. So, what we’ve done is thoroughly obvious; while it’s not easy to get everyone to agree, it’s obvious we should be capturing consumer-demand across all the platforms. And this is a very, very important indicator. The press was uniformly positive as well and I love what Mashable said because they’re always trashing magazines (laughs) and they said: if we assembled the study in an attempt to refute the assertion that magazine audiences are dwindling, the data vindicates them and that kind of said it all.

Also The Wall Street Journal said: magazine publishers can collectively point to some positive trends. Of course, we’re not saying that there aren’t problems because there certainly are, but we’re saying that the first step is to figure out what the consumers are doing, because there is no business if there isn’t consumer demand. And consumer demand is actually quite robust. Now this is not a report that shows everybody up, about 45 titles were down, so it’s pretty accurate.

That’s what this is all about. It’s really a reflection of how the business has changed, how we operate and how our content is consumed across multiple platforms. It’s the first step in capturing, measuring and communicating those reflections.

Samir Husni: I was just in Cannes at the Distripress Congress and my presentation was about “audience first.” And this is what Magazine Media 360 is saying: let’s focus on and be consumer centric. Why did we wait so long to do this?

Mary Berner: You know why? Because it’s really hard to get 147 brands and 30 CEO’s to agree. And I really didn’t wait that long, I’d been here two years and we got this done in six months. I also don’t think the industry was ready for it yet, I think we needed some critical mass in terms of multi-platform distribution content and frankly the third party research providers weren’t yet ready to get the data; so I think the time is right now.

The other question people ask is why don’t other media do it and my response is: they should. But it requires consensus, it requires industry consensus. And that’s a heavy lift.

Samir Husni: It’s as you said, magazine media is unlike any other medium, and you don’t get the same experience. If I’m watching a video, regardless of which platform, it’s the same video, where the magazine experience is completely different.

Mary Berner: All the content is created under a brand umbrella. So if I’m a Vogue person, the brand gives me permission to experience a whole lot of things under that umbrella. We’re the only media that’s actually set up well for that. CBS isn’t a brand. Other media are; I think ESPN is a brand; they actually do a great job at it.

Samir Husni: The new buzz phrase today is: print isn’t dead, it’s just in decline, but it’s still the cornerstone of our industry? Do you agree?

Mary Berner: I would say that print is a part of the consumer consumption experience, an extremely important part, but I would say that we haven’t told the story in regards to consumer demand up to this point. And when you do that, when you don’t tell the whole story, what fills that vacuum is a relentless and inaccurate story about one part of the business.

It’s inaccurate, like circulation. Everyone harps on newsstand. Newsstand is 8% of the total, 8%. And at its peak, 20 years ago, it was less than 20%. So there’s a kind of common narrative around print. Advertising paging over the last five years is down less than 8% in total. So, print has its challenges, but what isn’t even captured in those numbers is the migration of advertising dollars to other platforms. Therefore, it doesn’t tell an accurate story. We haven’t told an accurate advertising story or an accurate consumer-demand story yet.

Samir Husni: What do you think will be your major stumbling block? The honeymoon has been great, the reaction has been great; do you think it’s going to be smooth sailing from here or are you expecting some turbulence along the way?

Mary Berner: To be truthful, our attention in trying to figure out all the things that could and might go wrong ahead of time and addressing any and all challenges before we actually launched this, puts us in a position where we’ve asked and answered many of the stumbling blocks. Many of them had to do with methodology or transparency, things like that, so the only thing that I can imagine is maybe somebody won’t like their numbers.

I think the opportunity is that what we’ll see is a set of tools that will start people talking about it. How do we figure out how to use this to help us to buy?

Samir Husni: What are some of the criteria that you’re now going to use at The New York Times box score?

Mary Berner: It’s already changed. We’ve affected with this, just look at the numbers. They’re all up, two weeks in a row, a 100%. Let me tell you why The New York Times doesn’t use ad pages and why the entire industry was behind that, because it doesn’t tell an accurate story, by definition it tells an incomplete story. So, we don’t have something to replace that with, in terms of the advertising performance. We don’t, but until we do we have an obligation, in fact a responsibility, to stop reporting inaccurate data, because it is used to peg the vitality of an industry and it doesn’t do that. You could have had a spectacular PIB month and had a terrible advertising month. You could have had a terrible PIB month and a spectacular advertising month. It only captures the print performance. And as such, it’s just not comprehensive. And the reaction to that has been a little bit of, well, what am I going to use? But once I explain it to analysts and reporters, everybody gets it. You can’t argue with it, because it’s true.

Now what people will argue about is, they’ll say we need to get some replacement advertising data and what I’d like to remind the world of is, we’re the only industry that has released advertising data for decades as an industry. No other industry does it. We’ve been doing it and we’ve been doing it up to the point where it’s not accurate anymore. We had enormous transparency. Think about television, there’s no revenue numbers. They talk about the upfront when it’s good, but they don’t do it as an industry. Radio doesn’t, digital doesn’t; none of them do.

So we were in the forefront of transparency, but now that it’s not representative of the advertising performance of a brand, company or the industry, we have a responsibility to stop promoting and communicating it.

Samir Husni: You have a very nice feather in your cap now, so what’s next for Mary?

Mary Berner: This is just the beginning. I think it’s a good first step, but what we need to show is engagements, because we know from research in various companies the engagements in these brands of these multi-platform experiences are really extraordinary and that is a differentiator for magazine media and so, how do we do that? And I really wasn’t looking for a feather in my cap, I really wasn’t. (Laughs) But you can’t change the narrative about magazines until you start capturing and talking about magazine media. You have to start talking about the business the way the business is now.

Samir Husni: Thank you.